Dubai is one of the most active financial centres in the Middle East. Its banking infrastructure, regulatory clarity, and access to regional capital flows make it a strong base for monetary intermediation. This guide covers what activity code 6410.00 permits, who regulates it, and how to set up through Meydan Free Zone.
What Monetary Intermediation Covers
Activity code 6410.00 covers deposit-taking, credit intermediation, and interbank lending. Banks, credit institutions, and licensed financial intermediaries operate under this code. It permits raising funds from depositors and lending them to borrowers or counterparties.
The code does not cover insurance, investment management, or securities trading. Those activities carry separate codes and separate regulators.
| Activity code | 6410.00 |
|---|---|
| Activity name | Monetary intermediation |
| Licensed banks in UAE | Over 50 banks, including 22 foreign banks – Central Bank of the UAE |
| UAE banking assets | Over AED 4 trillion – Central Bank of the UAE |
| Primary regulator | Central Bank of the UAE (CBUAE) |
| Foreign ownership | 100% permitted in free zones – Invest in Dubai |
- Deposit-taking from retail and corporate clients
- Credit intermediation: lending funds raised from depositors
- Interbank lending and liquidity management
- Trade finance and letters of credit
Who Regulates This Activity
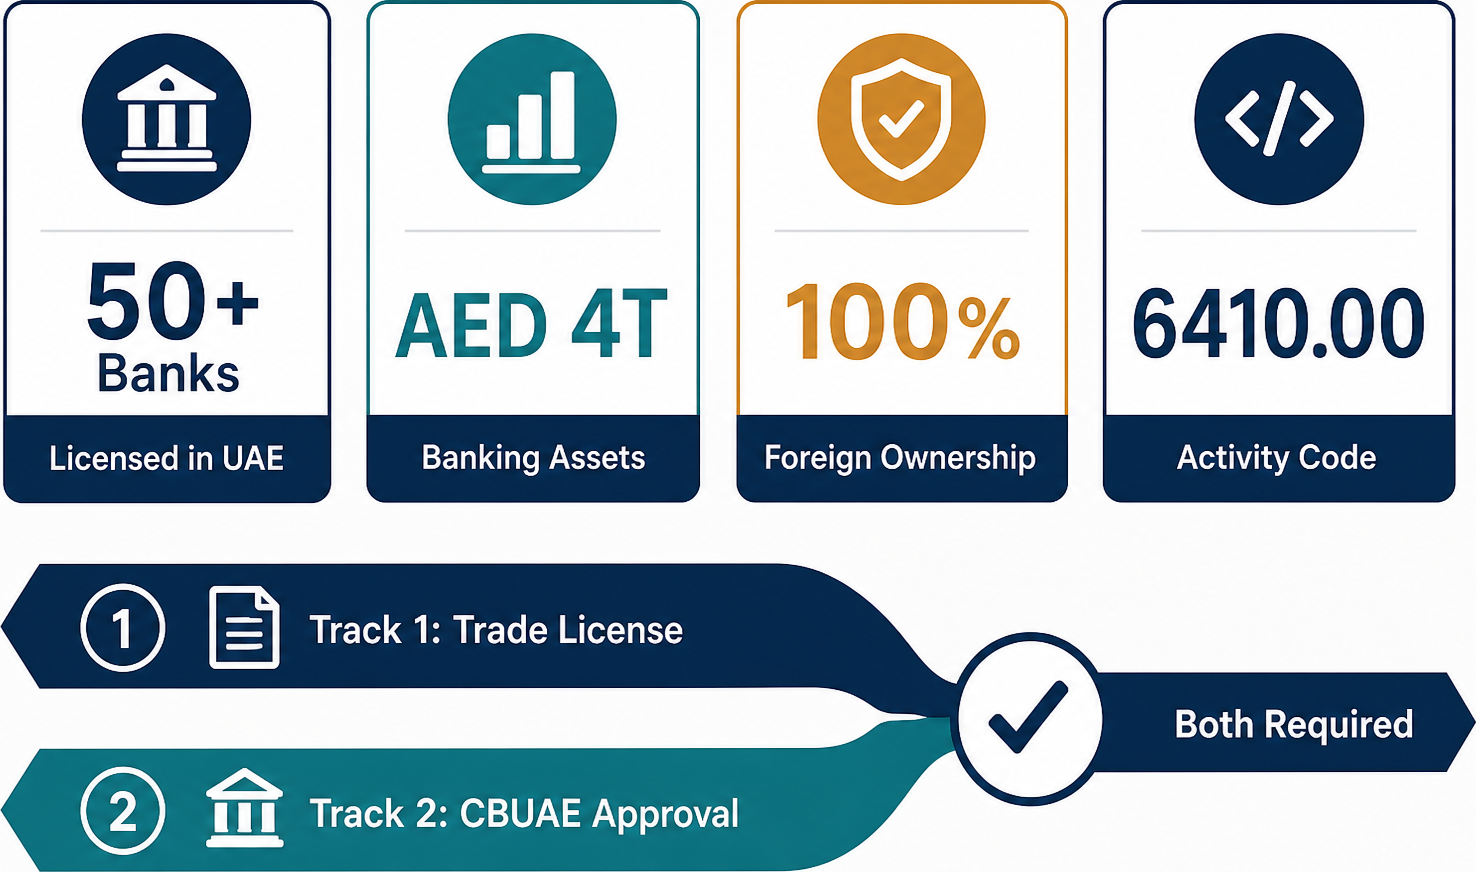
The Central Bank of the UAE sets the rules for all monetary intermediation. A trade license alone is not enough to operate. You also need a banking or financial institution license from the CBUAE before you take a single deposit or extend any credit.
The CBUAE checks capital adequacy, governance, and the fitness of directors and senior managers. These checks run in parallel with your trade license application. Plan for both from day one.
A Meydan Free Zone trade license acts as your commercial vehicle. The CBUAE approval is your operating permit. You need both.
| Factor | Mainland (DET) | Free Zone (Meydan Free Zone) |
|---|---|---|
| Client access | Open UAE market | Mainly international clients |
| Foreign ownership | 100% permitted | 100% permitted |
| CBUAE approval | Required | Required |
| Office requirement | Physical office required | Flexi-desk options available |
| Setup speed | Longer process | Faster trade license issuance |
Free Business Setup Cost CalculatorCalculate Now
Your Clients and Business Model
Your clients fall into 3 groups: retail depositors, corporate borrowers, and financial counterparties. Revenue comes from the interest margin between deposit rates and lending rates, plus fees on trade finance and interbank activity.
The UAE has a real SME lending gap. Large banks focus on big corporates. Smaller credit institutions can serve SMEs, traders, and regional businesses that need fast, flexible credit. That is a workable niche.
- Retail depositors seeking returns above savings rates
- SMEs needing working capital or trade finance
- Corporate clients with treasury and FX needs
- Regional counterparties using UAE as a financial gateway
How to Set Up via Meydan Free Zone
The setup runs in 2 tracks: the trade license and the CBUAE application. Start both at the same time. Waiting for one before the other adds months to your timeline.
- Step 1, book your trade name: Use the Company Name Check tool to confirm availability before you apply.
- Step 2, select activity code 6410.00: Confirm the code is listed in the Business Activities List for your chosen setup.
- Step 3, submit your trade license documents: Passport copies, business plan, and shareholder details go to Meydan Free Zone.
- Step 4, receive your trade license: Meydan Free Zone issues the license. This is your legal entity.
- Step 5, apply to the CBUAE: Submit your capital proof, governance documents, and fit-and-proper forms to the Central Bank.
- Step 6, meet capital requirements: The CBUAE sets minimum capital thresholds. Check current figures at centralbank.ae.
- Step 7, get your operating approval: Once the CBUAE approves, you can begin taking deposits or extending credit.
Visa eligibility starts once your trade license is issued. Meydan Free Zone offers flexi-desk options, which keeps your setup cost low in the early stage. You can also start your business remotely if you are not yet based in the UAE.
Compliance and Ongoing Duties
Monetary intermediation carries some of the heaviest compliance duties in UAE commercial law. The rules are not optional and the penalties for breaking them are serious.
AML and CFT You must have a full anti-money laundering and counter-financing of terrorism programme in place before you open. This covers customer due diligence, transaction monitoring, and staff training.
Reporting to regulators You report to the CBUAE and to the UAE Financial Intelligence Unit. Suspicious transactions go to the FIU right away. Routine reports go to the CBUAE on a set schedule.
Corporate tax Register with the Federal Tax Authority for UAE corporate tax. The standard rate is 9% on taxable income above AED 375,000.
Annual renewal and audit Your trade license renews each year. The CBUAE also runs periodic audits. Keep your records clean and your governance documents current.
- Customer due diligence on every account
- Transaction monitoring systems in place
- Suspicious activity reports filed with the FIU
- Annual CBUAE regulatory reporting
- Corporate tax filing with the FTA
- Trade license renewal each year
The Real Opportunity Here
The UAE banking industry holds over AED 4 trillion in assets. But the market is not saturated at every level. SME credit, trade finance for smaller importers, and cross-border lending for regional businesses are all areas where new entrants can build a workable book.
The dual-approval process is demanding. But it also keeps weak operators out. Once you are in, you are in a regulated, credible space with real barriers protecting your position.
Monetary intermediation in Dubai is a high-compliance activity. It rewards operators who are well-capitalised, well-governed, and serious about the regulatory process. The commercial opportunity is real for those who meet the bar.
Ready to Launch Your Business in Dubai?Let’s Connect
